New Mexico has some of the simplest car insurance rules in the country — and some of the most dangerous roads to be underinsured on, because nearly one in four drivers here carries no insurance at all. Here's how the state's rules actually work, from 25/50/10 to the uninsured-motorist protections written into state law, so you can set coverage that protects you instead of just satisfying the MVD.
New Mexico car insurance, in 60 seconds
- The legal floor is 25/50/10. That's $25,000 per person / $50,000 per accident for injuries you cause, and $10,000 for property damage — enough to register a car, rarely enough to survive a real accident.
- Nearly one in four drivers around you has no insurance. New Mexico's uninsured rate is the second highest in the nation. That single fact should shape your whole policy.
- Your insurer must offer you UM/UIM — and a sloppy rejection works in your favor. New Mexico law requires uninsured/underinsured motorist coverage to be offered at your liability limits, with any rejection in writing. Deficient paperwork means courts add the coverage back, stacked.
- Stacking is real money. Insure three cars with $25,000 UM/UIM each and New Mexico lets you combine them — $75,000 of protection when an uninsured driver hits you.
- There's a clear path to being properly covered. Match your limits to what you'd have to protect, keep UM/UIM equal to liability, then stack the legitimate discounts — and we'll review it with you for free.
New Mexico auto insurance — key facts
| Minimum bodily injury liability | 25/50 | NMSA 1978, Mandatory Financial Responsibility Act (verified Sept 2026) |
| Minimum property damage liability | $10,000 | NMSA 1978, MFRA (verified Sept 2026) |
| Fault system | At-fault (tort) | NM Office of Superintendent of Insurance (2026) |
| UM/UIM coverage | Must be offered at liability limits; written rejection required | NMSA 1978 § 66-5-301; 13.12.3 NMAC |
| UM/UIM stacking | Permitted across insured vehicles | NM case law under § 66-5-301 (verified Sept 2026) |
| Uninsured drivers | 24.1% — 2nd highest in the U.S. | Insurance Research Council, 2023 claims data (pub. 2025) |
| Full-coverage state average (2026) | ~$1,600–$2,200/yr | 2026 industry analyses (NerdWallet, Experian) — not a NM quote |
You renewed your car insurance, glanced at the total, and moved on. But on New Mexico roads, the coverage that decides whether a bad crash ruins you financially usually isn't the coverage you were thinking about when you bought the policy. Nearly one in four drivers here carries no insurance at all — the second-worst rate in the country — which means the most important question isn't "am I legal?" It's "what happens when the driver who hits me has nothing?" This guide walks through what New Mexico actually requires, the uninsured-motorist rules that quietly favor you, what coverage really costs in 2026, and how to tell whether your policy protects the life you have now.
What Car Insurance Does New Mexico Actually Require?
The short answer: Every registered vehicle in New Mexico needs at least 25/50/10 liability coverage — $25,000 per injured person, $50,000 per accident, $10,000 for property damage.
New Mexico's Mandatory Financial Responsibility Act sets the floor: liability coverage of 25/50/10. That's $25,000 to cover bodily injury you cause to any one person, $50,000 total for injuries per accident, and $10,000 for damage you do to someone else's property. Insurers writing auto policies here must also offer you uninsured/underinsured motorist coverage equal to your liability limits — more on why that offer matters so much in the next section.
Here's the problem: a real accident outruns those numbers fast. The average new vehicle now costs more than $10,000 can repair when it's totaled, and one night in a trauma unit can move past $25,000 before breakfast. In New Mexico, anything above your limits comes out of your own pocket — potentially including your wages and assets. The legal minimum keeps you street-legal; it does not keep you financially safe.
| Coverage | NM minimum | What we usually suggest |
|---|---|---|
| Bodily injury liability | 25/50 | 100/300 |
| Property damage liability | $10,000 | $100,000 |
| Uninsured/underinsured motorist | Offered — keep it | Match your liability, stacked |
| Medical payments | Not required | $5,000+ |
None of those upgrades is exotic. Moving liability from the state minimum to 100/300/100 typically costs far less than people assume, because the odds of a claim don't change — only the ceiling on what the policy will pay when one happens. We'll come back to how to think about the right limits for your New Mexico auto policy at the end.
Why Is Uninsured Motorist Coverage the Coverage That Matters Most Here?
The short answer: Because 24.1% of New Mexico drivers are uninsured — the second-highest rate in the nation — and state law is built to keep UM/UIM on your policy unless you very deliberately sign it away.
According to the Insurance Research Council's study of 2023 claims data, 24.1% of New Mexico motorists are uninsured — second only to Mississippi, and far above the 15.4% national rate. Add the drivers carrying only the bare 25/50 minimum, and the driver who hits you has decent odds of being unable to pay for what they did. Uninsured/underinsured motorist coverage (UM/UIM) is the part of your policy that steps in when that happens: your medical bills, lost wages, and pain and suffering, paid by your own insurer, up to your UM/UIM limits.
New Mexico law treats this coverage as seriously as the numbers suggest it should. Under NMSA 1978 § 66-5-301 and the Superintendent of Insurance's rules (13.12.3 NMAC), your insurer must offer UM/UIM equal to your liability limits, show you the premium for each level offered, and document any rejection in writing, incorporated into the policy it delivers to you. When that paperwork is deficient, New Mexico courts don't shrug — they reform the policy to include UM/UIM at your liability limits, stacked.
Stacking is the second thing every multi-car household here should understand. If you insure three vehicles with $25,000 of UM/UIM each, New Mexico lets you combine those limits into $75,000 of protection when an uninsured driver injures you. Across a family's policy, stacking is often the difference between a covered recovery and a financial hole. It's also why the rejection forms are so consequential — signing one away can waive far more protection than the premium it saves.
Is New Mexico a No-Fault State?
The short answer: No — New Mexico is an at-fault (tort) state: the driver who causes the crash is financially responsible for the harm.
After a crash in New Mexico, the at-fault driver's liability insurance is supposed to pay for the other side's injuries and property damage. You can file against their insurer, and if the harm exceeds their limits, they remain personally responsible for the rest. There's no personal-injury-protection mandate here and no restriction on your right to pursue the person who hurt you — the system is fault all the way down.
That sounds cleaner than it plays out, for one reason you already know: the driver who hits you has roughly a one-in-four chance of having no insurer to file against. Fault-based recovery only works when there's a policy on the other side. That's why the honest way to think about a New Mexico auto policy is in two halves — the liability half protects everyone else from you, and the UM/UIM half protects you from everyone else. Optional medical payments coverage is worth a look too: it pays early medical bills for you and your passengers regardless of fault, which bridges the gap while a liability or UM claim is sorted out.
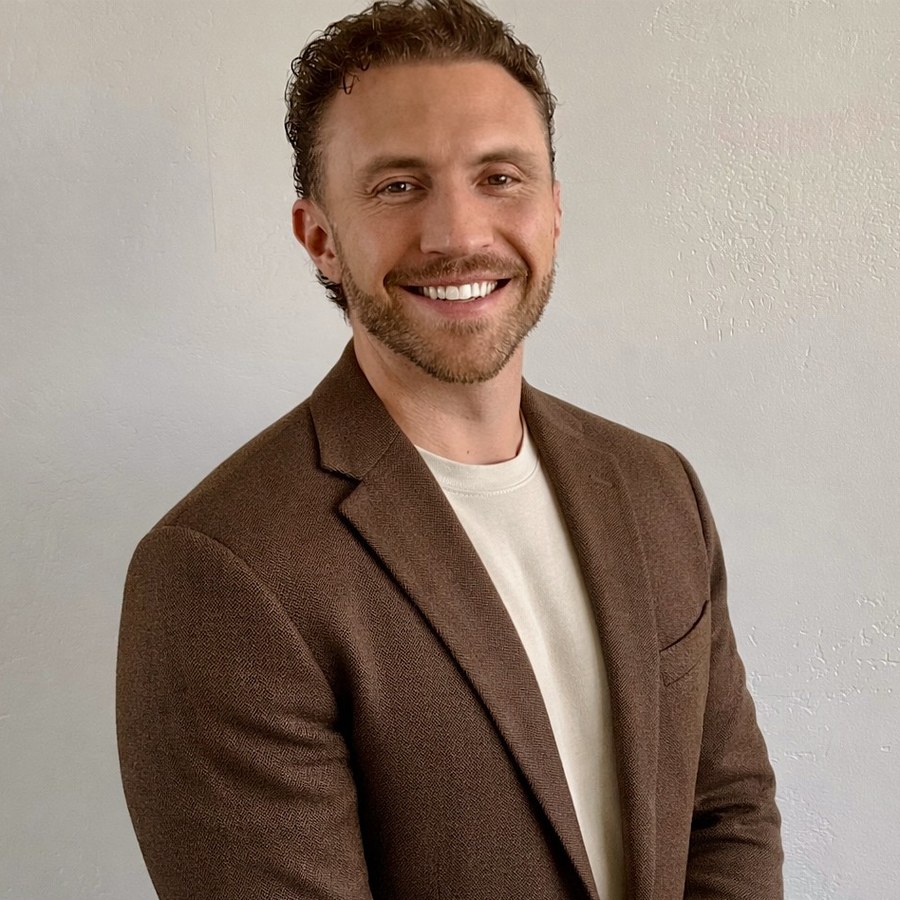
Wyatt Mace
Wyatt is a lifelong Farmington resident who founded The Mace Agencies in 2018. His team of nearly twenty carries roughly 18,000 policies in force from offices in Farmington and Albuquerque, licensed in New Mexico, Colorado, Arizona, Utah and Texas.
How Much Does Car Insurance Cost in New Mexico?
The short answer: 2026 analyses put New Mexico's full-coverage average roughly between $1,600 and $2,200 a year, with minimum-only policies commonly between about $500 and $1,000 — but those are study averages, not your quote.
Car insurance pricing is stubbornly personal, so treat any statewide number as an orientation point rather than a prediction. Industry analyses published in 2026 — NerdWallet's April analysis and Experian's mid-year marketplace data among them — put New Mexico's full-coverage average in the neighborhood of $1,600 to $2,200 per year, with state-minimum liability commonly landing between roughly $500 and $1,000. The spread between studies isn't error; it reflects different sample drivers, coverage levels and methods. New Mexico generally prices below the national average — one of the few pieces of good news in this guide.
What actually moves your number:
Where you park it
Location is the biggest swing in New Mexico — Albuquerque's theft and traffic push rates above the state average, while Farmington and much of the Four Corners sit below it.
What you drive
Repair and parts costs on newer trucks and SUVs push comprehensive and collision premiums up; older, cheaper-to-fix vehicles cost less to insure.
Your record
Tickets and at-fault claims raise your rate for years. A clean record is the most reliable discount there is.
Your choices
Deductibles, liability limits, UM/UIM and stacking decisions all move the premium — which is where a coverage review actually saves money.
Here's the part the rate-comparison sites bury: chasing the lowest headline number usually means buying the thinnest coverage, and in a state where a quarter of drivers are uninsured, thin coverage is where people get hurt financially. The smarter play is right-sizing the coverage first and then capturing every legitimate discount — which is the next section.
Say you're rear-ended on US 550 outside Bloomfield by a driver with no insurance at all — a roughly one-in-four proposition here. You need surgery and miss two months of work; your economic damages come to $60,000.
Illustrative figures only, not a quote or a guarantee of coverage. Your actual outcome depends on your policy terms and the facts of the claim.
Which Discounts Can New Mexico Drivers Actually Get?
The short answer: The reliable ones are bundling home and auto, safe-driving telematics programs, good-student discounts, paid-in-full and auto-pay credits — and an annual review to catch the ones you've started qualifying for.
Discount lists on the internet run long; the ones that reliably show up on real New Mexico policies are shorter. Bundling home (or renters) and auto with one agency is usually the largest single credit available to a typical household. Telematics and safe-driving programs reward how you actually drive — worthwhile for most people with a normal commute. Good-student discounts take real money off a teen driver's line if they keep the grades, and paid-in-full and auto-pay credits are free money for people who can swing the billing.
The discount families miss most isn't on any list — it's the review. Households change: a teen leaves for college, a commute shortens, a car gets paid off, a garage gets built. Each of those can move your premium, and none of them reports itself to your insurer. That's why we do free coverage reviews: not to sell you more, but to make sure the policy still matches the household paying for it.
What Happens If You Get Caught Driving Uninsured in New Mexico?
The short answer: It's a misdemeanor — and New Mexico's insurance database means a lapsed policy can get your registration suspended even if you're never pulled over.
New Mexico runs an Insurance Identification Database: carriers report active policies to the state, and the Motor Vehicle Division matches them against registrations. Let a policy lapse and the state can flag the vehicle and suspend the registration until proof of insurance is filed — no traffic stop required. Get cited driving uninsured and you're looking at a misdemeanor, fines, and a mark that makes your next policy more expensive.
The citation is honestly the small risk. The large one is causing a crash while uninsured: you remain personally liable for every dollar of harm, your license and registration are on the line, and you'll re-enter the insurance market as a high-risk driver. If money is the reason a policy lapsed, call us before it does — a bare-bones legal policy costs far less than the cheapest accident, and there's usually more room in the premium than people think.
How Do I Choose the Right Coverage — Not Just the Cheapest?
The short answer: Set liability limits that could survive a lawsuit, match UM/UIM to them — stacked — and only then tune deductibles and discounts.
Work the decision in order. First, liability: your limits should bear some relationship to what you'd have to protect if you caused a serious crash — for most working households that's 100/300/100 territory, not 25/50/10. Second, UM/UIM: match it to your liability limits and keep stacking if you insure multiple vehicles; in this state, it's the coverage most likely to actually pay you. Third, the car itself: comprehensive and collision make sense on anything financed or worth real money; on an old paid-off pickup, a higher deductible or dropping collision can be rational. Last, price: deductibles, billing credits and legitimate discounts — trimmed only after the protection is right.
Notice what's not on that list: buying the thinnest policy a comparison site can find. The cheapest policy in New Mexico is cheap because it does the least, in the state where the other driver is least likely to have coverage of their own. A twenty-minute conversation about your actual household beats an hour of anonymous quote forms — which is, candidly, the conversation we're here for.
The Bottom Line on New Mexico Car Insurance
The short answer: Carry more than 25/50/10, never reject UM/UIM, keep it stacked, and review the policy annually — that's the whole playbook.
New Mexico's rules are simpler than most states': 25/50/10 to be legal, fault-based recovery after a crash, and an uninsured-motorist statute that works hard to keep UM/UIM on your policy. The complication isn't the law — it's the roads, where nearly one driver in four has no insurance and plenty more carry only the minimum. Build your policy for that reality: real liability limits, UM/UIM matched and stacked, medical payments if the budget allows, and the discounts layered on top rather than in place of coverage.
If you're not sure where your current policy stands — what your UM/UIM limits are, whether they're stacked, whether a rejection form you don't remember is sitting in the file — that's a ten-minute check for us. Start a free quote or call (505) 600-4678 and a licensed New Mexico agent in Farmington or Albuquerque will read the policy with you, line by line.
Related Questions
Keep Exploring New Mexico Coverage
More from our Farmington and Albuquerque team — new guides are added to the hub as they publish.
New Mexico Auto Insurance
Coverage built around UM/UIM, stacking, and the limits that actually protect you.
Explore auto coverage → 🏠New Mexico Home Insurance
Homeowners coverage for New Mexico houses — and the bundle credit when you pair it with auto.
Explore home coverage → 🧭All New Mexico Insurance Guides
The full library — auto, home, renters, condo, landlord, life and more, organized by topic.
Browse the hub → ✅Free Coverage Review
A licensed local agent reviews your current policy — UM/UIM and stacking included — at no cost.
Start my free quote →About this guide. Written and reviewed by The Mace Agencies team, licensed New Mexico insurance professionals serving roughly 18,000 policies from our Farmington and Albuquerque offices, and licensed in New Mexico, Colorado, Arizona, Utah and Texas. We're a local Allstate agency, and this guide is educational. Every figure is drawn from the named sources cited above: the New Mexico Office of Superintendent of Insurance, NMSA 1978 (including § 66-5-301), and the Insurance Research Council. All of it is reviewed for freshness.
Last reviewed by The Mace Agencies team on September 8, 2026.